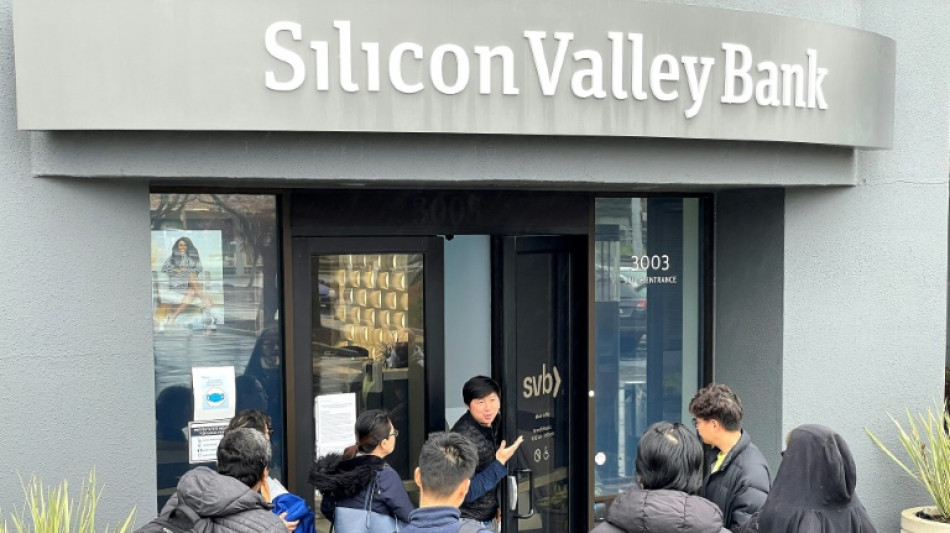
Interest rate risk: SVB's nemesis a well-known foe in banking / Photo: JUSTIN SULLIVAN - GETTY IMAGES NORTH AMERICA/AFP/File

Among the mysteries surrounding the collapse of Silicon Valley Bank, finance experts have fixated on the California lender's failure to practice basic risk management.
A catalyst for SVB's demise was the Federal Reserve's shift from near-zero interest rates to large interest rate increases to counter inflation, a reversal that immediately lowered the value of SVB's holdings linked to long-term US Treasury bonds.
Within the world of risk management, this issue -- referred to as "interest rate risk" -- is well known and relatively straightforward to address.
Banks manage this risk by hedging, purchasing futures contracts or other financial vehicles that rise in value in case a bank's holdings are devalued due to policy changes.
SVB's meager hedging operation "astounds me," said Clifford Rossi, a former risk management executive at Citigroup and a professor at the University of Maryland.
Rossi estimates SVB's hedging program should have been twice its size.
At the end of 2022, SVB reported $120 billion of these investment securities, or 55 percent of total assets, more than double the average of US banks.
A precipitating event in SVB's collapse was the March 8 disclosure that it sold $21 billion in securities at a loss of $1.8 billion to raise cash to fund operations.
If SVB had had in place an adequate hedging program, it would have generated enough profit to offset the effect of selling the Treasury-linked assets at a loss, said Kris James Mitchener, an economics professor at Santa Clara University in California.
"Why management chose not to (hedge) is a mystery thus far," Mitchener told AFP. "This is something we teach to undergraduates."
Mitchener noted that the Fed itself, in its role as a regulator, had not publicly spotlighted interest rate risk.
The Fed's 2022 stress tests on the largest banks did not include a scenario of sharply higher interest rates comparable to the one it has effected.
- 'Generally manageable' -
SVB officially failed on March 10, when California regulators directed the Federal Deposit Insurance Corporation to seize control of the bank and manage the return of funds to depositors.
Only days earlier, FDIC Chair Martin Gruenberg had highlighted interest rate risk at an event with the Institute of International Bankers.
Gruenberg noted that banks held about $620 billion in "unrealized losses" at the end of 2022, characterizing the matter as an "ongoing supervisory focus."
"The good news about this issue is that banks are generally in a strong financial condition, and have not been forced to realize losses by selling depreciated securities," Gruenberg said. "On the other hand, unrealized losses weaken a bank’s future ability to meet unexpected liquidity needs."
A December 2022 S&P Global Ratings report described unrealized losses as "generally manageable" for US banks, calling higher interest rates broadly "beneficial" to banks because they can charge more for loans, lifting net interest income (NII).
"However, we also recognize that if a bank were unexpectedly forced to realize losses on its securities, perhaps because of liquidity pressures, the benefit to NII and earnings from higher rates would very likely be insufficient to make up for the realized losses," S&P said.
- Contagion risk? -
In recent days, other midsized US banks that share traits with SVB have tanked on Wall Street.
First Republic, which has seen waves of investor selling, had much lower unrealized losses than SVB, but shared the tech-centered bank's heavy exposure to uninsured depositors.
A recent article in MarketWatch ranked 20 banks with the highest share of unrealized losses relative to size, with the top five including Comerica, Zion Bancorporation and KeyCorp, all of which have come under pressure on Wall Street.
Still, many banking experts consider SVB an outlier because of its confluence of risks, which also include its heavy exposure to a single industry in tech startups.
The largest US banks such as JPMorgan Chase and Bank of America have sophisticated hedging programs and a diversified deposit base. Many midsized banks do at least some hedging and had a smaller share of Treasuries compared to overall assets.
The hit from interest rates is "only a loss if you're forced to sell the asset," said Rohan Williamson, a finance professor at Georgetown University.
SVB was a case of "management failure or malpractice," he said.
Even if midsized banks do find themselves forced to sell assets to raise cash, new emergency Fed programs are designed to prevent an SVB-type scenario.
"At a minimum," the program "is buying the bank enough time to not face a run," said Mitchener. "It's a confidence game."
(B.Hartmann--BBZ)