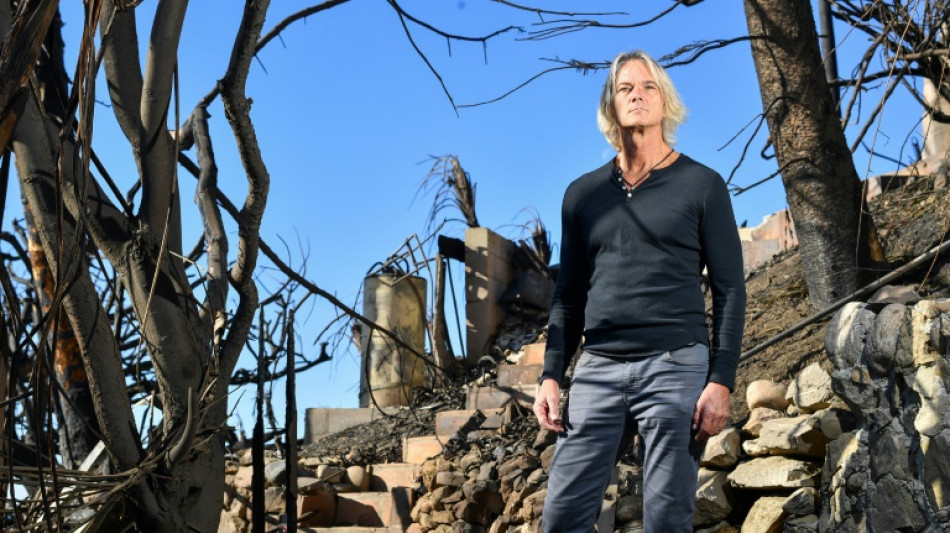
No home, no insurance: The double hit from Los Angeles fires / Photo: VALERIE MACON - AFP

As he looks at the ruins of his home razed when deadly fires tore through the Los Angeles area, Sebastian Harrison knows it will never be the same again, because he was not insured.
"I knew it was risky, but I had no choice," he told AFP.
Harrison is one of tens of thousands of Californians forced in recent years to live without a safety net, either because their insurance company dropped them, or because the premiums just got too high.
Some of them are now counting the crippling cost, after enormous blazes ripped through America's second largest city, killing more than two dozen people and levelling 12,000 structures, Harrison's home among them.
His own slice of what he called "paradise" stood on a mountainside overlooking the Pacific Ocean, where Malibu runs into the badly hit Pacific Palisades neighborhood.
The three-acre plot, which contained his home and a few other buildings, was always costly to insure, and in 2010 was already $8,000 a year.
When the bill hit $40,000 in the aftermath of the pandemic, he decided he simply couldn't afford it.
"It's not like I bought myself a fancy car instead of getting insurance," the 59-year-old said.
"It's just that food for myself and my family was more important."
For Harrison, a former actor, the emotional strain of losing the home he had lived in for 14 years is magnified by the knowledge that without a handout from the state or the national government, he has lost everything -- he even still has mortgage payments to make.
"I'm very worried, because this property is everything I had," he said.
- Climate costs -
Insuring property in California has become increasingly difficult.
Well-intentioned legislation that prevents insurance companies from hiking prices unfairly has collided with growing risks from a changing climate in a part of the world that now regularly sees devastating wildfires near populated areas.
Faced with burgeoning claims -- more damage, and higher repair costs because of the soaring price of labor and materials -- insurance companies turned tail and left the state en masse, dropping existing clients and refusing to write new policies.
Even enormous names in the market, like State Farm and Allstate, have pulled back.
Officials in state capital Sacramento have been worried for a while.
Last year Insurance Commissioner Ricardo Lara introduced reforms aimed at encouraging companies to return, including allowing them more leeway to increase their premiums to better match their costs.
But huge and inevitably very expensive fires erupting in what is supposed to be California's rainy season -- it hasn't rained for eight months around Los Angeles -- have reinforced the idea that the state is becoming uninsurable.
"I don't know now, because... my greatest fear was that we were going to have a catastrophe of this nature," Lara told the San Francisco Chronicle at the weekend.
Even the state-mandated insurer of last resort, a scheme designed to provide bare-bones coverage for those locked out of the private sector, could be struggling.
The California FAIR Plan was created in 1968 and is underpinned by every insurance company that operates in the state, as a requirement of their license to operate.
But the number of people now resorting to the scheme means its $200 million reserves are dwarfed by its liabilities. (A reinsurance sector helps to keep it liquid.)
- 'They're going to drop me' -
With the enormous losses expected from the Palisades and Eaton fires set to test the insurance sector even further, California has issued an edict preventing companies from dropping customers or refusing to renew them in certain affected areas, for one year.
That's scant consolation for Gabrielle Gottlieb, whose house in Pacific Palisades survived the flames.
"My insurer dropped a lot of friends of mine... and I'm concerned that they're going to drop me as well eventually," he told AFP.
"They're basically already putting it out there that 'lots of luck after a year!'"
Even in a best case scenario, home insurance looks set to be a lot more expensive in California, as state reforms filter through allowing increased prices in places more susceptible to wildfire.
"Real estate and taxes are already very high in California," said Robert Spoeri, a Pacific Palisades homeowner who was dropped by his insurer last year.
"If the insurance gets even higher, who is going to want to live in this state?"
(P.Werner--BBZ)