Europe’s electric car boom exposes a widening market divide

Europe’s battery-electric car market moved from steady expansion to genuine acceleration in the first half of 2026. Registrations rose far faster than the wider new-car market, and June pushed the technology beyond a quarter of all new cars sold. Yet the same figures reveal a continent divided between mature electric markets, rapidly scaling mass markets and countries where battery power remains a marginal choice.
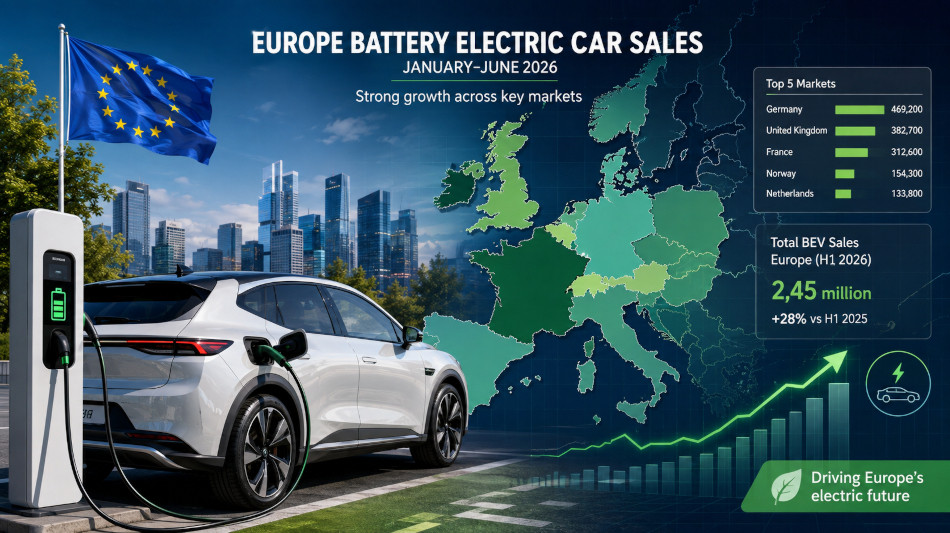
The headline figures are unequivocal. Across the European Union, the European Free Trade Association countries and the United Kingdom, 1,608,200 new battery-electric cars were registered between January and June. That was an increase of 35.1 per cent from the same period a year earlier. The total passenger-car market grew by a much slower 6.1 per cent to 7,232,066 vehicles, lifting the battery-electric share to 22.2 per cent.
The additional 418,094 battery-electric cars almost exactly matched, and slightly exceeded, the increase of 416,634 vehicles in the entire European market. In aggregate, battery power accounted for all net market growth while declines and gains among other powertrains offset one another. Battery-electric registrations also narrowly exceeded pure-petrol registrations across the wider region, at 1,608,200 cars compared with 1,590,767. The margin was small, but symbolically important. The half-year figures remain provisional, yet their direction is unmistakable.
Momentum strengthened markedly at the end of the period. June alone produced 360,843 battery-electric registrations, 51 per cent more than a year earlier, and a market share of 25.6 per cent. In practical terms, more than one new car in four was fully electric during the month.
Within the European Union, the structural change is even clearer. Battery-electric cars increased their share from 15.6 per cent to 20.7 per cent in one year. Petrol fell to 22.2 per cent and diesel to 7.5 per cent, leaving battery power only 1.5 percentage points behind petrol. Hybrid-electric cars remained the largest individual powertrain category with 37.3 per cent, while plug-in hybrids reached 9.8 per cent. Europe is therefore not moving through a simple one-for-one replacement of combustion engines. It is passing through a layered transition in which full electric, plug-in hybrid and conventional hybrid technologies are advancing at different speeds.
Three markets now determine European scale
Germany, the United Kingdom and France have become the centre of gravity. Together they registered 894,147 battery-electric cars in the first half, equivalent to almost 56 per cent of the European total. More significantly, these three countries generated roughly two-thirds of the entire net increase in battery-electric registrations across the region.
Germany remained the largest market with 368,006 registrations, up 48 per cent, and a battery-electric share of 24.8 per cent. The United Kingdom followed with 284,579 cars, an increase of 26.6 per cent, and a 25 per cent share. France recorded the fastest expansion of the three, rising 62.9 per cent to 241,562 registrations and a share of 28.2 per cent.
The French result is particularly revealing because the country’s overall new-car market grew by only 1.8 per cent. Electric growth was therefore driven chiefly by substitution within the market rather than by a broad sales boom. By June, the battery-electric share had reached 28.4 per cent in Germany, 30 per cent in the United Kingdom and 29.6 per cent in France. The largest European car markets are no longer merely catching up with the early adopters. They are approaching the point at which an electric car is a mainstream default rather than a specialist alternative.
The percentage leaders tell a different story
The countries with the highest electric shares remain concentrated in northern Europe, but their figures describe different stages of maturity. Norway recorded a battery-electric share of 97.6 per cent, although registrations grew by only 1.3 per cent to 71,662. That modest volume increase is less a sign of weakness than a consequence of saturation. There is little remaining combustion demand to displace in the new-car market.
Denmark was the more striking growth story. Battery-electric registrations rose by 41.2 per cent to 80,707 and accounted for 79.9 per cent of all new cars. Finland reached 47.8 per cent, Sweden 41.5 per cent and Iceland 42.4 per cent. Belgium and the Netherlands also remained highly electrified, with shares of 36.1 per cent and 36.5 per cent respectively.
The Dutch market illustrates how strongly timing and policy can affect national figures. First-half battery-electric registrations fell by just 45 cars, a decline of 0.1 per cent, making the Netherlands the only European market to record a decrease. Yet June registrations jumped by 42.2 per cent and the monthly share reached 44.2 per cent. A flat six-month result can therefore conceal a sharp change in direction.
Rapid growth does not always mean mass adoption
The reverse problem is visible in southern and eastern Europe, where spectacular growth rates often start from a very small base. Italy registered 79,434 battery-electric cars, an increase of 77.7 per cent, but their share of the national market was still only 8.5 per cent. Spain rose by 36.7 per cent to 63,201 cars, yet remained below 10 per cent of the market.
Poland reached only 5.3 per cent, despite a 15.6 per cent rise in volume. Croatia produced the most dramatic percentage increase in Europe at 349.7 per cent, but that represented only 1,781 cars and a market share of 4 per cent. Slovenia, by contrast, more than doubled registrations and raised its share to 16.5 per cent, suggesting that some smaller markets can move quickly once incentives, model availability and charging access begin to align.
These differences explain why hybrids remain so important. In markets where purchase prices are more sensitive, home charging is less accessible or the vehicle fleet is older, a conventional or plug-in hybrid can appear to offer a lower-risk route into electrification. The result is a multi-speed market: full battery power leads in the north and west, while partial electrification still performs much of the transitional work in the south and east.
The electric-car market is no longer a single-brand story
June’s model rankings briefly restored a familiar picture, with the Tesla Model Y and Model 3 leading battery-electric sales. The broader market, however, has become markedly more competitive. Strong volumes are now coming from compact and family models offered by Renault, Skoda, BMW, Kia and Mercedes-Benz, while Chinese and Chinese-owned brands are adding further pressure on price, equipment and development cycles.
This widening choice matters more than any single monthly ranking. Earlier phases of European electric-car adoption depended heavily on premium vehicles, company cars and a limited number of recognisable models. The current phase is being driven by a denser product field that covers small hatchbacks, family crossovers, executive saloons and lower-priced sport utility vehicles. Consumers are increasingly able to compare electric cars against one another rather than against a petrol equivalent alone.
Affordability is improving, but it remains the decisive constraint. Falling battery costs and the arrival of smaller models helped reduce the sales-weighted average purchase price of a battery-electric car in Germany by about 6 per cent during 2025. Low-cost electric models nevertheless remain a small part of the European catalogue, and the purchase-price gap is still most visible in precisely those countries where market shares remain below 10 per cent.
Charging growth must now match vehicle growth
Europe’s public charging network is expanding, with publicly accessible charging points in the European Union reaching 1,170,493 by June, an increase of 18 per cent in a year. The direction is positive, but the network remains unevenly distributed and registrations are currently growing faster than infrastructure.
National totals also disguise the practical experience of drivers. A dense motorway network of rapid chargers does not solve the problem faced by residents of apartment buildings who cannot charge overnight. Nor does a high number of urban charging points necessarily provide confidence for rural drivers or small businesses operating beyond major corridors. The next phase of the transition will depend less on the existence of chargers in aggregate and more on their reliability, speed, location and price. Fleet economics may be even more important. Only around four in ten new European cars are registered by private buyers. The majority are bought by company fleets, dealerships or rental businesses, which means that tax treatment, leasing costs and expected resale values exert enormous influence over the market.
That influence later passes into the used-car sector. Around eight in ten Europeans buy their cars second-hand, with the proportion even higher among low- and middle-income households. Yet the value retained by battery-electric cars after several years has weakened more sharply than the wider market. Across five large European countries, average battery-electric value retention fell from about 50 per cent in 2022 to 35 per cent in 2025. Lower used prices can help later buyers, but uncertain residual values raise risk for leasing companies and can increase monthly payments for new customers.
Policy has become part of the market architecture
The strongest markets are not relying on a single instrument. They combine manufacturer emissions requirements, company-car taxation, purchase support, charging investment and a steadily broader range of vehicles. Germany’s 2026 programme offers income-linked support of between €1,500 and €6,000 for eligible purchases and leases. France has maintained targeted purchase assistance and reopened social leasing in July, with electric cars offered for less than €200 a month to qualifying households. The United Kingdom provides discounts of up to £3,750 on approved lower-priced models. Denmark, meanwhile, froze the registration-tax rate for zero-emission cars at 40 per cent for 2026 rather than allowing the planned increase to 48 per cent.
The design of these measures is changing. Broad subsidies for early adopters are giving way to support linked to income, vehicle price, family circumstances, manufacturing standards or environmental performance. That is fiscally more defensible, but it also makes stability essential. Abrupt changes can pull demand forward, postpone purchases or produce misleading monthly swings.
The second half will test the depth of demand
June’s 25.6 per cent battery-electric share was 3.4 percentage points above the first-half average, indicating that momentum accelerated as the year progressed. It would still be unsafe to assume that every month will follow the same line. Delivery schedules, fleet renewals, incentive deadlines and model launches can all create temporary surges.
The more important test is whether Europe can convert high growth into broader access. Germany, France and the United Kingdom have demonstrated that large markets can move rapidly when regulation, incentives and product supply reinforce one another. Denmark shows how tax architecture can make electric power the standard choice. Norway shows what a mature end state looks like. Italy, Spain, Poland and much of south-eastern Europe show how far affordability and infrastructure still have to travel.
Europe has passed the stage at which battery-electric cars can be dismissed as a niche. They are now the principal source of growth in the new-car market and are closing rapidly on petrol as an individual powertrain. The unresolved question is no longer whether the transition is happening, but whether it can become affordable, geographically balanced and durable without permanent emergency support.
Europe has an electric-car boom. It does not yet have a single European electric-car market.
K.Leight