BCC
1.0400

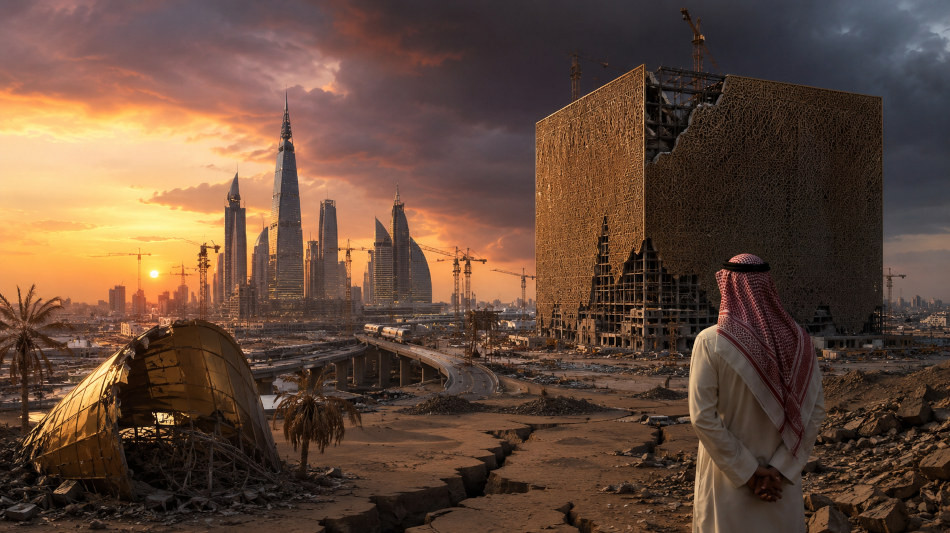
At the edge of the Red Sea, the future is no longer arriving on schedule. Excavations still scar the desert, cranes remain on the horizon and selected construction packages continue. Yet the promise that once gave these works their meaning has changed. The Line, presented as a 170-kilometre revolution in urban life, has been deprioritised. Trojena has lost the Asian Winter Games that were meant to impose a hard deadline on its mountain resort. Major rail and dam contracts have been terminated. In Riyadh, work beyond preliminary foundations on the vast Mukaab structure has been suspended while its financing and feasibility are reconsidered.
These are not routine delays on one difficult building site. They amount to a strategic retreat from the most theatrical version of Saudi Arabia’s economic transformation. The kingdom is not bankrupt, and Vision 2030 is not a total failure. Saudi society and its economy have changed substantially since the programme was launched a decade ago. But the original formula behind its most spectacular projects is failing on its own terms. Costs have outrun credible returns, deadlines have collided with engineering reality, foreign capital has remained cautious and the state can no longer pretend that every ambition deserves simultaneous funding.
Vision 2030 began in 2016 as an answer to a structural danger. Saudi Arabia had built extraordinary wealth on oil, but hydrocarbons also made public finances vulnerable to production decisions, price cycles and the long-term energy transition. A young population needed jobs, private enterprise needed room to grow and the state required new sources of revenue. The programme promised a larger private sector, more tourism, greater participation by women in the labour market, new industries and a more open social environment.
Neom, announced in 2017, became the programme’s most potent symbol. The Line, unveiled in 2021, was its purest expression. The plan envisaged two mirrored walls rising roughly 500 metres, standing 200 metres apart and extending for 170 kilometres through the north-western desert. It was intended eventually to house nine million people in a car-free city powered by renewable energy, with daily needs reachable within minutes and high-speed transport connecting the entire settlement.
The audacity was not incidental. Saudi Arabia was trying to create a brand large enough to alter how the world viewed the kingdom. Spectacle was meant to attract investors, tourists, engineers and global companies. It also served a domestic political purpose. The megaprojects embodied a new social contract in which national pride, employment and modern lifestyles would be delivered through rapid development directed from the centre.
By 2026, however, the contrast between the rendering and the construction site had become impossible to disguise. The first phase of The Line had already been reduced from the original public expectations. In January, the 2029 Asian Winter Games at Trojena were postponed, and Kazakhstan subsequently took over the event. In March, a contract worth about 4.7 billion dollars to build dams for Trojena was ended, along with a related steel package. In May, the contract for Neom’s connector high-speed railway was terminated. In June, another state-backed developer confirmed that it would take over the troubled Sindalah island resort, assess what remained unfinished and attempt to bring it back to life. Saudi officials continue to distinguish between cancellation and reprioritisation. Politically, that distinction protects the long-term vision and avoids declaring a flagship idea dead. Commercially, it matters less to contractors whose packages have ended, employees whose work has slowed or event organisers who have moved elsewhere. A project can remain alive as a concept while ceasing to be a serious near-term commitment.
The reset was formalised in April 2026 when the Public Investment Fund presented its new five-year strategy. The fund, with assets of roughly 925 billion dollars, intends to direct about four-fifths of its investment towards the domestic economy. Its priorities now place greater weight on industry, logistics, advanced manufacturing, clean energy, tourism, urban development and artificial intelligence. Neom remains within the portfolio, but The Line has lost priority. The message is clear. Saudi Arabia still wants transformation, but it increasingly wants projects that can generate revenue, attract partners and support productive sectors before they consume another generation of capital.
The change is driven first by arithmetic. A sovereign wealth fund worth hundreds of billions of dollars is not a limitless current account. Much of its value is tied up in companies, securities and long-term assets. The fund must also support domestic champions, finance infrastructure, invest abroad, absorb losses and preserve its own ability to borrow. At the end of 2024, its high-profile giga-project holdings suffered a write-down of about 8 billion dollars. That did not threaten the fund’s survival, but it exposed the widening gap between promotional valuations and the economic value of projects facing delay, redesign and uncertain demand.
Pressure on the state budget has intensified as well. Saudi Arabia entered 2026 expecting a deficit of 165 billion riyals, equivalent to about 44 billion dollars, and financing needs of roughly 217 billion riyals. In the first quarter alone, the deficit reached about 125.7 billion riyals as spending rose during severe regional disruption. Emergency conditions made the imbalance worse, but they did not create the underlying problem. The kingdom had already committed itself to a construction programme, global events and industrial expansion on a scale that assumed stronger and more dependable revenues.
The central contradiction is that diversification away from oil is still largely financed by oil. When crude prices and production are strong, the state can fund non-oil sectors aggressively. When revenue weakens, the very programme designed to reduce dependence on hydrocarbons must be slowed. Estimates of the oil price required to balance the Saudi budget have at times stood above 90 dollars a barrel, well above the level seen during much of the recent period. The government can borrow, sell assets and draw on reserves, but each option has a cost. A wealthy state can finance almost anything for a while. It cannot finance everything at once without sacrificing returns, liquidity or future flexibility.
This does not erase the achievements of Vision 2030. By 2025, non-oil activity accounted for about 55 per cent of real output, while the private sector’s contribution reached roughly 51 per cent. Non-oil growth remained stronger than the oil economy. Unemployment among Saudi citizens fell close to the original 7 per cent target, and women’s participation in the labour market rose beyond 35 per cent, far above the level before the reforms. Tourism expanded rapidly, the original goal of 100 million annual visits was reached years early when domestic and international trips were counted together, and more than 700 international companies established regional headquarters in the kingdom. Those gains are real, but they do not settle the more difficult question of whether diversification has become self-sustaining. A large share of non-oil demand is still created, guaranteed or indirectly supported by the state. Construction companies depend on public contracts. Banks finance government-linked activity. Hospitality and entertainment benefit from subsidised events and infrastructure. Private businesses grow around spending by the Public Investment Fund. The result is a more varied economy, but not yet an economy fully independent of public capital or oil-funded demand.
Foreign direct investment reveals the gap. Inflows reached about 35.5 billion dollars in 2025, a significant increase from earlier years but still far below the ambition of attracting 100 billion dollars annually by 2030. The regional headquarters policy has persuaded many companies to establish offices in Riyadh, especially because access to state contracts can depend on a local presence. An office, however, is not the same as large-scale risk capital committed to an untested city, an expensive resort or a new industrial ecosystem.
International investors judge projects by cash flow, governance, legal predictability and the ability to exit. They may admire the ambition of The Line without accepting the risk of financing it. The absence of enough outside capital therefore matters twice. It leaves the Saudi state carrying more of the cost, and it signals that the expected commercial returns have not persuaded the market. Public money can launch a sector and reduce early risk. It cannot permanently substitute for customers, profits and independent investment.
The engineering challenge has been just as severe. Conventional cities grow in increments. Roads, utilities, districts and transport networks can be expanded as demand appears. The Line reversed that logic by concentrating an urban system inside a single, extreme geometry. Its appeal depended on enormous infrastructure being available before a large population arrived. Transport, ventilation, power, water, waste management, emergency access and vertical circulation all had to work at exceptional scale from the beginning.
A linear city also creates forms of fragility that promotional images do not show. Redundancy becomes harder when so much movement depends on a narrow axis. Construction sequencing becomes less flexible. Every alteration affects connected systems. The mirrored exterior, monumental height and desert environment add maintenance demands. The vast quantities of steel, concrete and glass required for the structure create an immense embodied carbon burden before the first resident can claim a low-emission lifestyle. A project marketed as environmentally revolutionary must account for the environmental cost of being built at all.
Trojena exposed a similar conflict between symbolism and practicality. A mountain resort with skiing, artificial water features, hotels and elite events offered a striking image of Saudi Arabia defying climate and geography. Yet the sporting deadline also forced the project to reveal whether its infrastructure could be delivered on time and at a defensible cost. The transfer of the 2029 Winter Games to Kazakhstan was therefore more than an event-management decision. It removed one of Neom’s clearest tests of execution.
Governance magnified these technical and financial risks. Centralised authority allowed Saudi Arabia to announce reforms, mobilise land and capital, and begin projects with remarkable speed. The same structure made it difficult to challenge assumptions early. When an initiative is closely associated with national leadership, managers and consultants have powerful incentives to preserve the appearance of momentum. Costs are treated as problems to be solved later, timetables become political commitments and scepticism can be mistaken for disloyalty.
The result was a portfolio in which design often preceded demand and publicity preceded feasibility. Reviews and leadership changes eventually forced a more realistic assessment, but only after tens of billions of dollars had been committed. The lesson is not that ambitious states should avoid ambitious projects. It is that ambition requires stronger independent appraisal precisely because political authority is capable of moving so quickly.
The human cost has also damaged the credibility of the transformation. Communities in the Neom region faced displacement, and three members of the Howeitat tribe were sentenced to death in cases linked to resistance against eviction for the project. Across the broader construction drive, migrant workers have faced recurring allegations of unpaid wages, unsafe conditions and inadequate investigation of deaths. These are not peripheral public-relations difficulties. A development model that promises a futuristic quality of life cannot treat the people building it as an expendable input.
Environmental credibility is equally important. Neom’s renewable-energy claims sit uneasily beside the carbon-intensive materials, desalination, cooling and ecological disruption associated with building at unprecedented scale in a fragile landscape. Saudi Arabia can make genuine progress in solar power, wind power and green hydrogen while still making poor environmental choices in individual projects. Sustainability is not established by branding. It is demonstrated through lifecycle emissions, water use, land impact and transparent measurement. Some parts of Neom may yet produce durable value. The port at Oxagon is already operating and has gained strategic relevance as companies test Red Sea routes around disrupted Gulf shipping. The green hydrogen complex has secured long-term partners and is approaching production, although the economics of the global hydrogen market remain uncertain. Data centres, renewable power, industrial logistics and export infrastructure have clearer customers and can be developed in stages. They do not require millions of people to relocate to an unproven urban form before the business case works.
This is why the retreat from The Line does not necessarily mean the end of Neom. It may instead transform Neom from a fantasy city into a more conventional industrial and energy zone with selected tourism projects. Such an outcome would be far less dramatic than the original promise, but potentially far more useful. The challenge will be admitting how much of the old vision has been abandoned rather than preserving it indefinitely as a distant aspiration.
The wider investment portfolio is undergoing the same selection. Infrastructure for Expo 2030 and the 2034 football World Cup now has firm deadlines and immediate political value. Diriyah and Qiddiya sit closer to major population centres and can draw on existing demand. Mining, logistics, manufacturing and artificial intelligence offer clearer links to exports and productivity. These priorities still carry risks of cost inflation, overbuilding and state dependence, but they are easier to defend than a 170-kilometre mirrored city whose commercial purpose remained secondary to its image.
The claim that Vision 2030 is the world’s most expensive plan is rhetorically powerful but financially imprecise. There is no single audited price tag for the entire programme. It is a portfolio of budgets, sovereign investments, company borrowing, property development, infrastructure, sporting commitments and private ventures spread across many years. Even so, its scale is extraordinary, and the opportunity cost is real. Money devoted to an unfinished monument cannot also be invested in schools, water security, established cities, small businesses or export industries.
Saudi Arabia’s most serious failure is therefore not the decision to retreat. Rephasing an unrealistic project is better than continuing simply to protect prestige. The deeper failure is the credibility gap created by years of presenting distant possibilities as near-term certainties. Investors, contractors and citizens cannot easily distinguish a firm commitment from a promotional concept when official language treats both with equal confidence.
The kingdom still possesses formidable advantages. It has vast energy assets, substantial reserves, a large sovereign wealth fund, comparatively manageable public debt, a strategic location and a young domestic market. It can absorb mistakes that would overwhelm a poorer country. Saudi Arabia is not running out of money. It is running out of cheap choices, and each new commitment now competes with obligations already made.
The final years before 2030 will show whether the government can turn recalibration into discipline. Success will depend less on new renderings and more on productivity, export earnings, education, legal certainty, private investment and project selection. It will require the state to close ventures that cannot justify their costs, even when they carry political prestige. It will also require more transparent accounting of what has been spent, what has been built and what economic return is expected.
Saudi Arabia is failing only if failure means that money and command have not been able to abolish economics. The country itself is not collapsing, and the broader reform programme has delivered changes that would have seemed unlikely a decade ago. What has collapsed is the illusion that spectacular architecture can substitute for markets, institutions and time. The desert is unforgiving to illusions. It preserves foundations, trenches and unfinished structures long after the presentation has changed. If Saudi Arabia learns from that evidence, the retreat from its most extravagant projects could mark the moment Vision 2030 becomes more credible. If it does not, the kingdom may be left with the most expensive monuments ever built to ambition without accountability.